Arvexa Financial
AboutLoan OptionsDebt ReliefHow It WorksFinance EducationBlogFAQ
(888) 901-6908OFFICE OPENMon-Fri, 8 AM-5 PM Pacific Time
Review My Options
The Arvexa Journal
Managing payments

Why Credit Card Minimum Payments Can Keep You in Debt

Paying on time matters, but the minimum is not designed around your preferred payoff date. Your statement can help expose the difference.
Arvexa Financial Editorial Team
Published October 25, 20263 min readChecking reading status...
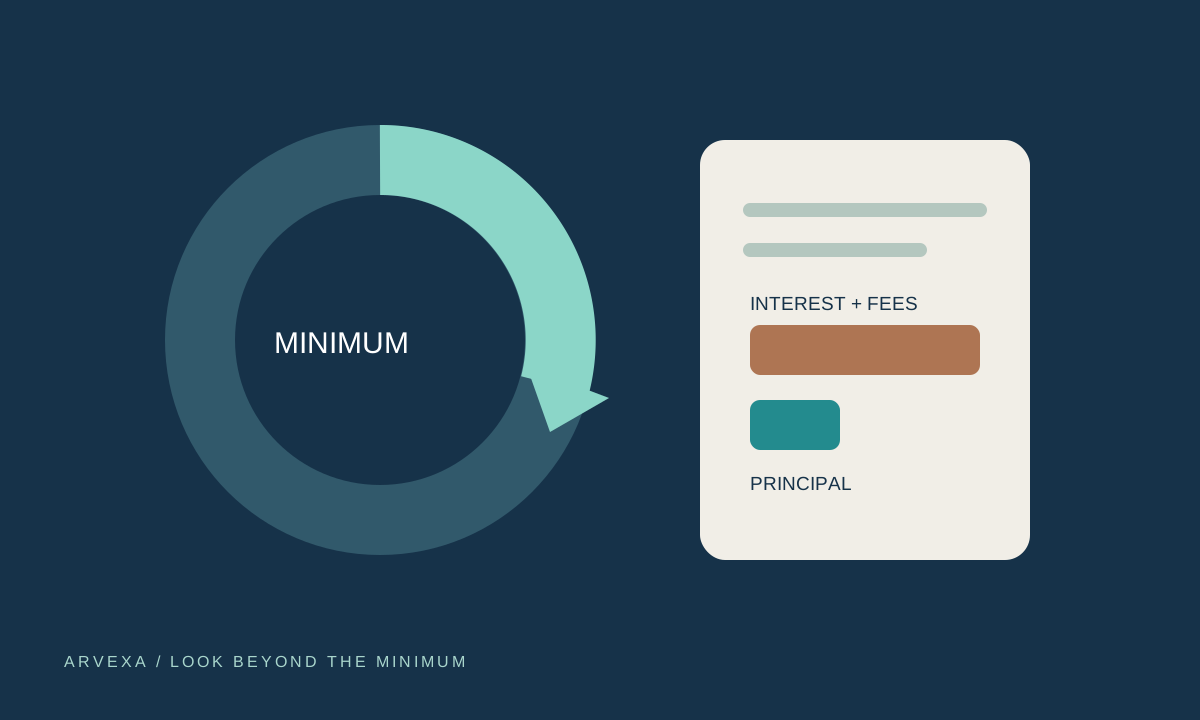
A circular payment path beside a statement showing interest and principal portions.
A payment can satisfy the minimum while making limited progress against the balance.

In this article

  1. Interest can absorb much of the payment
  2. Read the payoff information on your statement
  3. Three checks before changing your plan
Your next step, on your terms.

Explore loan options without affecting your credit score.

Check My Options
The short version

What to take away

  • Part of a payment may cover interest and fees rather than reduce principal.
  • A shrinking minimum can extend repayment if you keep paying only that amount.
  • Statement payoff estimates rely on assumptions, including no new purchases.

A credit-card minimum is the amount required under the account's current terms, not a promise that the balance will disappear quickly. Paying at least the required amount on time matters, but it may leave a long repayment path. To understand why, separate the payment into interest, fees, and the portion that actually reduces the balance.

Interest can absorb much of the payment

As a rough illustration, a $5,000 balance at a 24% annual rate represents about $100 of interest over a month using a simplified annual-rate-divided-by-twelve estimate. If the payment were $150, only about $50 would reduce principal before other charges. Actual card interest depends on daily balances, billing-cycle length, applicable rates, and the agreement; this is not a statement calculation.

Cards can also carry multiple balances with different APRs. Purchases, transfers, and cash advances may not share the same rate or grace-period treatment. Read the rate table and transaction categories before assuming every dollar has the same cost. Fees or new purchases can offset the principal reduction from an otherwise timely payment.
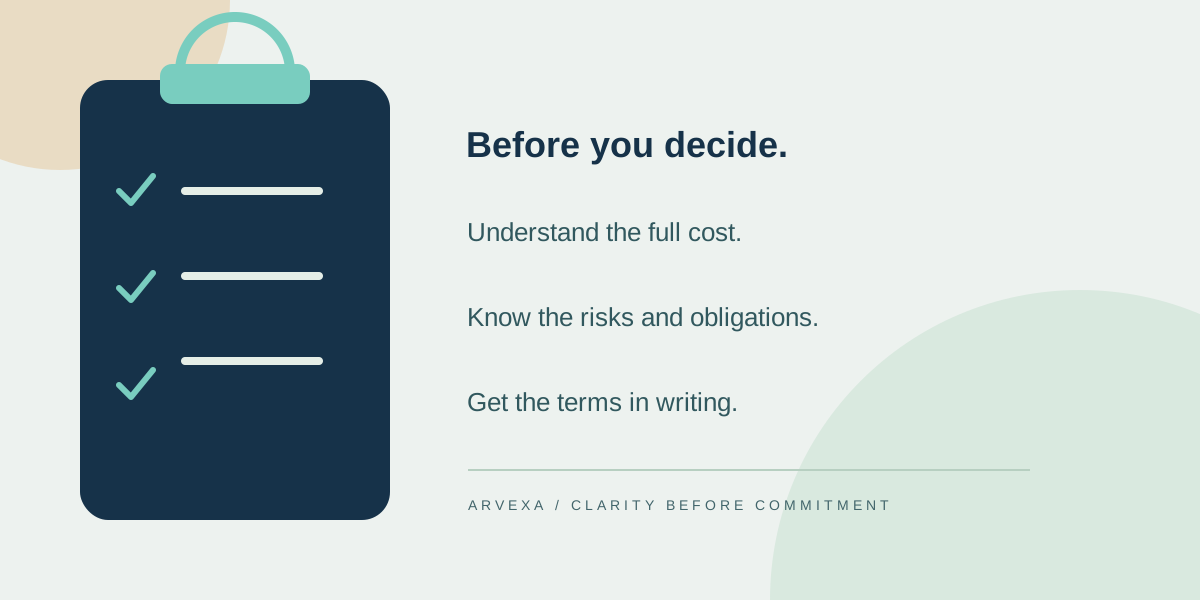
A three-point decision checklist: understand the full cost, know the risks and obligations, and get the terms in writing.
A useful checkpoint for any financial decision, no matter which path you explore.

Read the payoff information on your statement

Many U.S. card statements show a minimum-payment payoff estimate and a payment amount designed to repay the current balance in about three years. Those figures provide a useful comparison, but they depend on stated assumptions. They are not a guarantee if you add purchases, miss payments, incur fees, or experience rate changes.

A minimum based partly on the outstanding balance may decline as the balance falls. If you reduce your payment every time the minimum drops, repayment can slow. A fixed affordable payment above the minimum may make progress more predictable, provided it continues to satisfy any higher required payment and your budget can sustain it.

Three checks before changing your plan

  • Record the balance, rate, required minimum, due date, and statement payoff estimate for each account.
  • Compare an affordable extra payment with the effect of new spending and irregular expenses.
  • If the minimum itself is unaffordable, contact the issuer promptly rather than relying on an optimistic payoff calculator.

A consolidation offer can be worth comparing, but do not compare only its payment with today's minimum. Include origination fees, the full term, and total repayment. Reusing the paid-off cards can leave you with both the new loan and new card balances.

Disclosure: Illustrations are simplified education, not a loan offer or an account-specific calculation. Arvexa is not a lender. Actual costs, credit effects, and repayment outcomes depend on your agreements and behavior.

Sources & further reading

  • CFPB: credit-card consumer resources
  • CFPB: help when card payments are unaffordable

Checking your reading status...

Marked read when you reach this ending. Saved only in this browser, with no login. Clearing site data removes your reading history. Marking unread keeps it unread for the rest of this visit.
Clarity is a good place to start

Let’s talk about your next move.

Explore personal loan options or ask questions about debt relief. Checking loan options uses a soft credit inquiry. There is no obligation to proceed.

Review My Options (888) 901-6908

Educational information, not individualized financial, legal, or tax advice. Arvexa is not a lender. Approval, savings, and outcomes are not guaranteed.

Keep the clarity going

All articles
  • Two conversation bubbles above a payment calendar and a manageable budget.
    Managing payments

    Can't Pay Your Credit Card? Ask About a Hardship Program

    Your card issuer may have options before you consider a new loan or settlement. Here is how to prepare for that conversation.

    Published October 25, 20263 min readChecking reading status...
  • Two ordered staircases representing smallest-balance and highest-interest payoff priorities.
    Managing payments

    Debt Snowball vs. Avalanche: Pick a Payoff Plan You Can Maintain

    One approach prioritizes quick account wins; the other targets interest costs. Both depend on an affordable budget and consistent payments.

    Published October 25, 20263 min readChecking reading status...
  • An itemized medical bill beside assistance paperwork and a payment-plan calendar.
    Managing payments

    Medical Bills You Can't Afford: Check Assistance Before Borrowing

    Before converting a medical bill into new borrowing, ask whether the amount is correct and whether the provider offers financial assistance.

    Published October 25, 20263 min readChecking reading status...
Arvexa Financial

Arvexa Financial helps everyday people find the right financial path, from personal loan offers to debt relief and money education, with clear guidance, professional support, and a straightforward first step.

Your Choice, Always: Comparing loan offers or reviewing other options never obligates you. We do not pressure any specific outcome. Any action is solely the customer's independent decision.

Partnered with ACDR-Accredited Debt Relief Providers

Arvexa agent certificationAll agents OCCAM CFHA certifiedConsumer Financial Hardship Advocate
(888) 901-6908

Explore

  • About
  • Loan Options
  • Debt Relief
  • How It Works
  • Finance Education
  • Blog
  • FAQ

Legal

  • Privacy Policy
  • Your California Privacy Choices
  • Terms
  • Disclosures
  • Do Not Sell or Share My Personal Information / Your Privacy Choices

Loan marketplace powered by Engine by MoneyLion (ML Enterprise Inc., formerly Even Financial), NMLS #1475872. Arvexa Financial and Engine are not lenders. Participating lenders make credit decisions and set final loan rates and terms.

Arvexa Financial is not a lender, law firm, or tax advisor. We are a consumer-focused financial marketplace that connects people with personal loan offers, debt relief options, and educational resources with clarity and integrity. Loan offers, approval, rates, and terms are determined by participating lenders. Independent third-party debt relief providers may offer services if a customer separately chooses to proceed. Outcomes vary, and debt resolution programs are not available in all states.

© 2026-2027 Arvexa Financial LLC & AuraLogic Solutions. All rights reserved.