Arvexa Financial
AboutLoan OptionsDebt ReliefHow It WorksFinance EducationBlogFAQ
(888) 901-6908OFFICE OPENMon-Fri, 8 AM-5 PM Pacific Time
Review My Options
The Arvexa Journal
Costs & transparency

Personal Loan APR and Origination Fees: What You Actually Receive

The amount approved, the amount deposited, and the total repaid may be three different numbers. Put all three on the comparison sheet.
Arvexa Financial Editorial Team
Published October 25, 20262 min readChecking reading status...
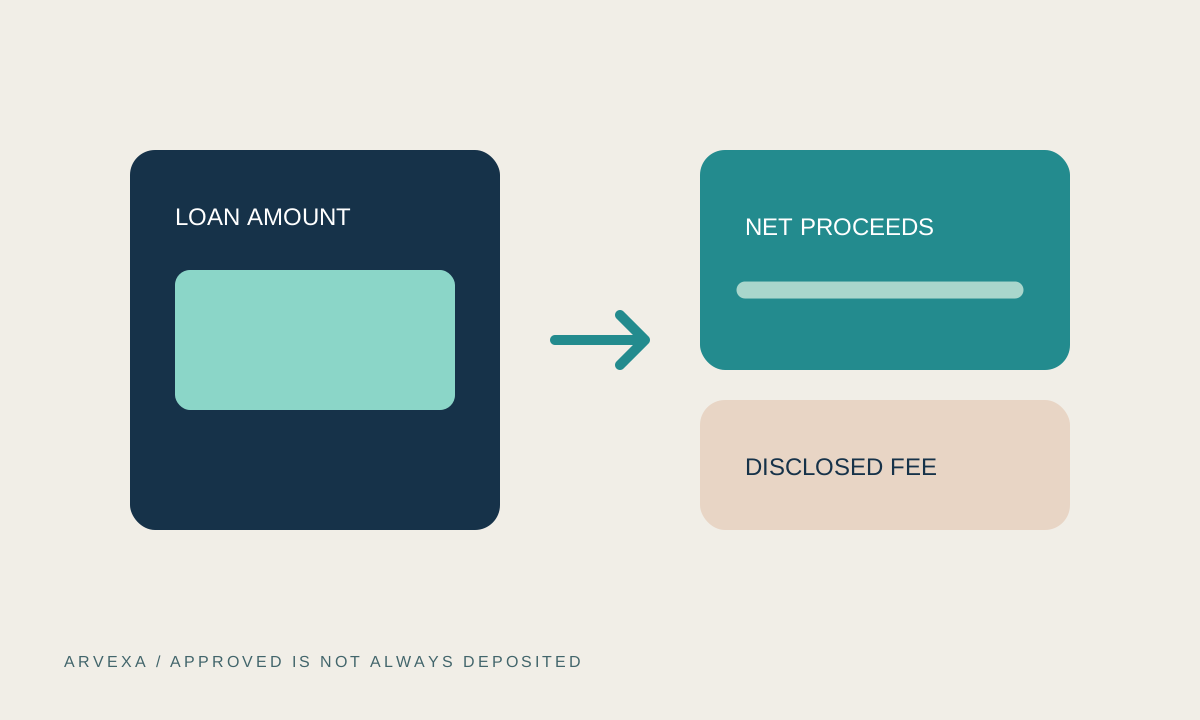
A loan amount divided into a disclosed fee and net proceeds beside a repayment total.
Compare the money received with every payment owed, not the headline rate alone.

In this article

  1. Interest rate and APR are not interchangeable
  2. Check the amount that actually reaches you
  3. Put competing offers on one page
Your next step, on your terms.

Explore loan options without affecting your credit score.

Check My Options
The short version

What to take away

  • APR incorporates interest and applicable borrowing charges; it is not just the interest rate.
  • A fee withheld from proceeds can leave less cash than the loan's face amount.
  • Compare term and total repayment as well as APR and monthly payment.

A personal-loan offer can show several numbers that sound like the price: interest rate, APR, origination fee, monthly payment, and total repayment. They answer different questions. Before consolidating debt, you need to know both the amount available to repay existing balances and the full obligation you are accepting in exchange.

Interest rate and APR are not interchangeable

The interest rate describes the cost of borrowing principal. APR expresses a broader annualized borrowing cost that incorporates interest and applicable finance charges. The CFPB explains this distinction using loan disclosures. Compare APR with APR rather than comparing one provider's interest rate with another provider's APR.

APR is useful, but it does not replace the payment schedule or capture every possible contingent cost. Late fees, optional products, and other charges require separate attention. A lower APR over a much longer term may still produce a larger dollar cost than a shorter, affordable loan.
A three-point decision checklist: understand the full cost, know the risks and obligations, and get the terms in writing.
A useful checkpoint for any financial decision, no matter which path you explore.

Check the amount that actually reaches you

Imagine a hypothetical $10,000 loan with a 5% origination fee withheld from proceeds. The fee would be $500 and the net proceeds would be $9,500. If you need $10,000 to repay existing cards, that leaves a $500 gap. You would still owe the loan according to its full contract terms; the withheld fee is not a reduction of the obligation.

Providers may collect or finance fees differently. Do not assume this example describes your offer. Ask for the amount financed, finance charge, net disbursement, payment schedule, and total of payments in the actual agreement. If the lender pays creditors directly, confirm how any shortfall or residual interest will be handled.

Put competing offers on one page

  • Record the requested amount, approved amount, fee, and usable proceeds.
  • Compare APR, fixed or variable rate, term length, monthly payment, and total repayment.
  • Check prepayment rules and whether optional products are truly optional.
  • Include any remaining old balance or trailing interest in the overall plan.

Avoid adding the same fee twice when totaling costs: it may already be incorporated into a disclosed finance charge or payment schedule. If the numbers do not reconcile, ask the lender to explain them before signing. A clear answer is more useful than assuming the lowest payment is automatically the best value.

Disclosure: Hypothetical fee example, not a loan quote or offer. Arvexa is not a lender. Actual APR calculations, charges, proceeds, eligibility, and terms come from the lender and applicable disclosures.

Sources & further reading

  • CFPB: the difference between interest rate and APR

Checking your reading status...

Marked read when you reach this ending. Saved only in this browser, with no login. Clearing site data removes your reading history. Marking unread keeps it unread for the rest of this visit.
Clarity is a good place to start

Let’s talk about your next move.

Explore personal loan options or ask questions about debt relief. Checking loan options uses a soft credit inquiry. There is no obligation to proceed.

Review My Options (888) 901-6908

Educational information, not individualized financial, legal, or tax advice. Arvexa is not a lender. Approval, savings, and outcomes are not guaranteed.

Keep the clarity going

All articles
  • A settlement agreement and Form 1099-C beside a folder of tax records.
    Costs & transparency

    Debt Settlement and Taxes: What a Form 1099-C May Mean

    A reduced payoff may have a tax side. Keep the settlement records and get advice before assuming the forgiven amount is either fully taxable or automatically excluded.

    Published October 25, 20263 min readChecking reading status...
  • A magnifying glass over an itemized statement, showing why the full cost matters.
    Costs & transparency

    How Debt Relief Fees Work — and When They Are Earned

    Settlement fees cannot be earned until a creditor agreement is reached, you approve it, and a payment is made. Learn the structure — and why dollar totals matter more than percentages.

    Published October 24, 20263 min readChecking reading status...
  • Two jars balanced on a scale, representing emergency reserves alongside debt repayment.
    Savings & debt planning

    Emergency Fund or Pay Off Debt? How to Think About Both

    Sending every spare dollar to debt can feel productive—until the next surprise bill. A practical framework helps you weigh interest costs against financial breathing room.

    Published October 25, 20264 min readChecking reading status...
Arvexa Financial

Arvexa Financial helps everyday people find the right financial path, from personal loan offers to debt relief and money education, with clear guidance, professional support, and a straightforward first step.

Your Choice, Always: Comparing loan offers or reviewing other options never obligates you. We do not pressure any specific outcome. Any action is solely the customer's independent decision.

Partnered with ACDR-Accredited Debt Relief Providers

Arvexa agent certificationAll agents OCCAM CFHA certifiedConsumer Financial Hardship Advocate
(888) 901-6908

Explore

  • About
  • Loan Options
  • Debt Relief
  • How It Works
  • Finance Education
  • Blog
  • FAQ

Legal

  • Privacy Policy
  • Your California Privacy Choices
  • Terms
  • Disclosures
  • Do Not Sell or Share My Personal Information / Your Privacy Choices

Loan marketplace powered by Engine by MoneyLion (ML Enterprise Inc., formerly Even Financial), NMLS #1475872. Arvexa Financial and Engine are not lenders. Participating lenders make credit decisions and set final loan rates and terms.

Arvexa Financial is not a lender, law firm, or tax advisor. We are a consumer-focused financial marketplace that connects people with personal loan offers, debt relief options, and educational resources with clarity and integrity. Loan offers, approval, rates, and terms are determined by participating lenders. Independent third-party debt relief providers may offer services if a customer separately chooses to proceed. Outcomes vary, and debt resolution programs are not available in all states.

© 2026-2027 Arvexa Financial LLC & AuraLogic Solutions. All rights reserved.